US Bond Yields Hit 2007 Highs: Why the Fed Decision May Not Be Enough
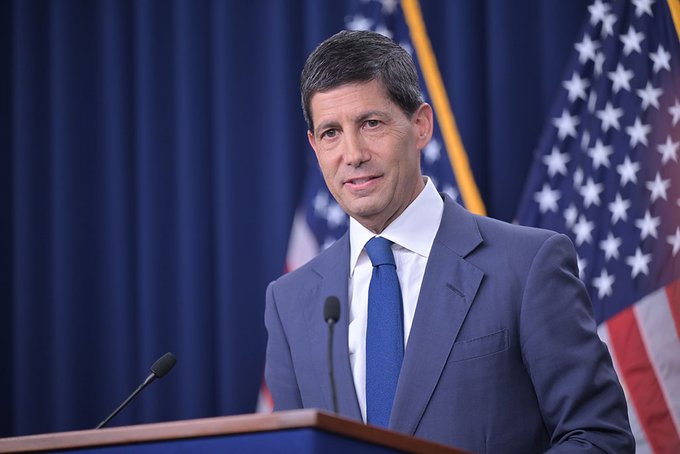
The 10-year Treasury yield has crossed 5% as oil-driven inflation, fiscal concerns and Fed rate expectations reshape the outlook for global markets. (Image Fed Reserve)
By S. JHA
The 10-year US Treasury yield has crossed 5% for the first time since 2007 as markets confront a difficult combination of inflation, oil prices, fiscal pressure and a potentially hawkish Federal Reserve.
Mumbai, September 15, 2026 — The US Treasury market is sending a message that equity investors may find increasingly difficult to ignore: the era of assuming that interest rates will eventually return to much lower levels is being challenged by a new inflation and fiscal risk premium.
The benchmark 10-year US Treasury yield climbed to around 5.04% on Tuesday, its highest level since 2007, before easing back. The move came as investors positioned ahead of the Federal Reserve’s September 15-16 policy meeting, with markets increasingly pricing in a possible 25-basis-point rate increase.
But the significance of the move goes beyond the Fed.
The Fed is only one part of the equation: The immediate focus is on the Federal Reserve. A rate increase would signal that policymakers remain more concerned about persistent inflation than about the pressure higher borrowing costs could place on economic activity.
Market expectations have shifted sharply. Reuters reported that some major Wall Street institutions moved towards forecasting a September hike, while futures markets were assigning a very high probability to a 25-basis-point increase.
Yet the rise in the 10-year yield cannot be explained entirely by expectations for the Fed’s overnight policy rate.
Longer-term Treasury yields also incorporate expectations about inflation, government borrowing, economic growth and the compensation investors demand for holding long-duration debt.
That is where the current market signal becomes more significant.
Oil has become an inflation problem again: Crude oil prices have moved sharply higher amid the continuing Middle East conflict and disruptions to energy infrastructure. Brent crude has moved above $100 a barrel, adding another potential source of inflation just as central banks are trying to keep price pressures under control.
Higher oil prices create a difficult policy combination.
They can push headline inflation higher while simultaneously reducing consumers’ purchasing power and increasing business costs. For the Fed, that makes an aggressive easing cycle harder to justify.
The result is a market increasingly worried about higher-for-longer rates.
The fiscal question may matter even more: The other structural issue is the enormous amount of US government debt that has to be financed.
Investors are demanding higher yields at a time when Treasury issuance remains substantial and concerns about the long-term fiscal position of the United States have returned to the centre of the bond market debate. Reuters noted that significant debt issuance, resilient economic growth and long-term fiscal uncertainty are among the forces pushing yields higher.
This creates a potentially important feedback loop.
Higher yields increase the government’s borrowing cost. Higher borrowing costs can increase future fiscal deficits. Larger deficits can require more debt issuance, which in turn may require investors to demand still higher yields.
That is why the 5% threshold matters psychologically as well as economically.
Why equities cannot ignore the bond market: The 10-year Treasury yield is effectively a benchmark for the global cost of capital.
When risk-free yields rise materially, investors have to reassess the premium they are willing to pay for equities, particularly high-growth companies whose valuations depend heavily on future earnings.
The recent market reaction reflects that tension. Global stocks weakened as Treasury yields climbed, with investors increasingly treating the bond market as a larger risk than several of the other concerns occupying markets this year.
For technology and AI-linked stocks, the issue is particularly important. Higher discount rates reduce the present value of future earnings, while higher financing costs can also affect the enormous capital expenditure cycle associated with AI infrastructure.
What markets should watch after the Fed decision: The most important question may not be whether the Fed raises rates by 25 basis points.
It is what happens to the 10-year yield after the decision.
If yields fall following a hike, markets could interpret the move as a policy adjustment that is already largely priced in.
If yields remain above 5% or move substantially higher, however, the market may be signalling that the problem is bigger than the Fed funds rate.
That would suggest investors are demanding a larger premium for inflation, fiscal risk and long-duration US debt.
A Fed hike is a monetary-policy event. A sustained rise in long-term Treasury yields is a broader repricing of the US economic and fiscal outlook.
The forward-looking market signal: The bond market is therefore becoming the clearest early-warning indicator for global investors.
The immediate risk is that higher oil prices keep inflation elevated, forcing the Fed to maintain a restrictive stance even as financial conditions tighten.
The longer-term risk is that investors begin demanding structurally higher returns to hold US government debt because of inflation and fiscal uncertainty.
For India and other emerging markets, the consequences could extend beyond Wall Street. A stronger dollar and higher US yields can put pressure on emerging-market currencies, foreign portfolio flows and domestic bond yields.
The September Fed decision will therefore matter. But the bigger story may already be unfolding in the Treasury market.
If the 10-year yield stays above 5%, markets may have to start treating higher global borrowing costs not as a temporary reaction to one Fed meeting, but as a structural feature of the post-pandemic financial landscape.
Follow The Raisina Hills on WhatsApp, Instagram, YouTube, Facebook, and LinkedIn



About The Author