UPI MDR Explained: Who Really Pays for “Free” Payments in India?
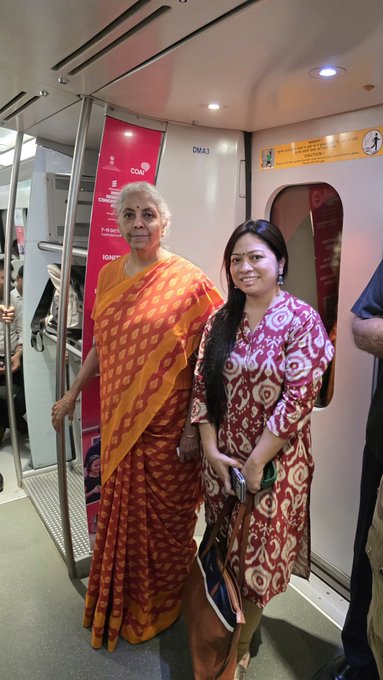
Union Finance Minister Nirmala Sitharaman travelled on the Delhi Metro en route to an interaction with beneficiaries of the PM MUDRA Yojana in New Delhi. (Sitharaman office on X)
By P. SESH KUMAR
The new UPI MDR framework keeps person-to-person transfers free, but raises bigger questions over merchant costs, NPCI surpluses, payment infrastructure and competitive neutrality.
New Delhi, September 18, 2026 — UPI may still feel “free” to most Indians, but the economics behind the world’s largest digital payments ecosystem are becoming harder to ignore. The new Merchant Discount Rate (MDR) framework preserves zero charges for person-to-person transfers and merchant payments up to Rs 2,000, while introducing charges for specified transactions above that threshold. The policy raises a larger question: who ultimately pays for the infrastructure, security and growing costs behind UPI—and how transparent is the ledger?
All person-to-person UPI transfers remain free irrespective of value. All merchant payments up to Rs 2,000 remain at zero MDR. Small merchants, including those falling within the specified P2PM framework and receiving up to Rs 1 lakh per month, remain protected. The Government estimates that about 96 per cent of P2M transactions by number will remain unaffected.
For specified merchant transactions exceeding Rs 2,000, the general MDR is 0.4 per cent, capped at Rs 300 once the transaction reaches Rs 75,000. Specified sectors including railways, telecommunications, insurance, fuel and agricultural inputs face a flat Rs 5 charge on qualifying transactions, while capital-market payments attract 0.02 per cent subject to the Rs 300 ceiling. Five per cent of MDR collections is earmarked for a fund intended to widen small-merchant adoption.
Most importantly, the Government explicitly says the MDR is neither a tax nor an amount collected by Government or NPCI. It is to be distributed among participating banks, PSPs and application providers. Customers are not to be charged it directly, and UPI apps are prohibited from imposing hidden platform charges under the framework.
That last fact sharpens the NPCI-surplus argument rather than making it irrelevant.
If NPCI itself does not collect this new MDR, and NPCI already generates substantial surpluses, then the principal sustainability justification must relate to the financing needs of other parts of the ecosystem.
Those needs therefore deserve separate quantification.
The Fee Is Small. The Change in Principle Is Not
At 0.4 per cent, the arithmetic appears modest.
A Rs 3,000 qualifying transaction generates Rs 12 of MDR. A Rs 10,000 payment generates Rs 40. A Rs 50,000 payment generates Rs 200. Once the general cap is reached, the charge stops rising beyond Rs 300.
The India Today argument is that the public-policy significance may nevertheless be larger than the amounts involved. “Free” is not merely another price point. Zero has a psychological character that Rs 1 does not.
For years, UPI was marketed, experienced and socially understood as something that could be used without transaction charges. The new regime preserves that experience for individuals and for the overwhelming majority of transactions, but it modifies the absolute proposition.
That creates what might be called the one-paisa problem.
Moving a price from Rs 100 to Rs 101 is a one-per-cent change.
Moving it from zero to Rs1 is conceptually different because a previously absent charging mechanism now exists.
The Case for MDR
There is a substantial case for permitting some commercial transactions to contribute directly to the infrastructure they use.
UPI is no longer an experimental platform that needs only enough capacity to demonstrate feasibility. It is critical national infrastructure processing tens of billions of monthly transactions. Cybersecurity must be upgraded continuously. Fraud detection is increasingly computationally intensive. Data centres, AI infrastructure, redundancy, dispute handling and rural expansion require continuing investment. NPCI’s reported FY2025-26 expenditure growth itself illustrates that scale creates costs as well as efficiencies.
There is also an equity argument within the payment system. It is relatively easy to justify public support for a Rs 50 payment to a street vendor because financial inclusion and merchant formalisation create social benefits. The economic rationale for taxpayers indefinitely subsidising the payments infrastructure associated with a Rs 50,000 commercial purchase by an affluent customer at a large merchant is less self-evident.
A limited MDR can also give banks and payment companies a direct commercial incentive to improve acceptance, uptime, fraud controls and merchant servicing rather than treating UPI merely as a customer-acquisition channel to be monetised through unrelated financial products.
These are economic considerations supporting the sustainability case. They do not determine what the rate should be; that requires cost evidence.
The Case for Caution
The objections are equally concrete.
First, merchants ultimately treat MDR as a business cost. A formal prohibition on adding a separate UPI surcharge prevents direct pass-through at checkout, but it cannot prevent the economic cost from affecting overall margins and, over time, prices.
Second, thresholds can alter behaviour. At Rs1,999 the MDR is zero; immediately above Rs 2,000 a different regime begins. Merchants may split payments, alter invoicing practices, encourage alternative instruments or–in some cases–prefer cash. Whether that occurs materially should be measured rather than assumed.
Third, UPI’s success has generated benefits beyond the parties to an individual transaction: reduced dependence on cash, easier bookkeeping, formal transaction records, financial inclusion and network effects. A purely private cost-recovery calculation may therefore undervalue its broader public benefits.
Fourth, the extraordinary scale of UPI may itself have reduced per-transaction infrastructure costs dramatically. Any sustainable MDR model should distinguish fixed infrastructure cost from marginal transaction cost rather than merely dividing an industry-wide expenditure figure by transaction volume.
And fifth, the existence of substantial NPCI surpluses means the word “sustainability” needs disaggregation. Which participant is unsustainable? At what rate of return? After which subsidies? After which existing charges? After accounting for what savings?
Those questions do not prove that MDR is unnecessary. They identify the evidence required to determine whether the chosen mechanism matches the actual funding problem.
UPI Transactions Soar while Fraud Incidents Call for Caution
The U.S. Complaint: More Complicated Than “America Says UPI Is Unfair”
The extract from the 2025 USTR National Trade Estimate is genuine, but its status needs precision.
The NTE is a U.S. Government inventory of barriers and distortions affecting American trade and investment. It is designed to identify measures Washington seeks to change; it is not a WTO judgment that India has violated international law. USTR itself describes the report as an instrument for identifying barriers that the U.S. Government seeks to remove.
The 2025 report said Indian electronic-payment policies appeared to favour domestic suppliers and described NPCI as “state-owned.” It portrayed NPCI’s 30 per cent transaction-volume cap as a limit on foreign electronic-payment suppliers and separately raised concerns about the National Common Mobility Card and the qSPARC standard.
That description was open to challenge.
NPCI’s original November 2020 announcement says explicitly that the 30 per cent cap was applicable to “all Third Party App Providers (TPAPs)”, with the stated objective of addressing risks as UPI scaled. It was not drafted as a nationality-specific limitation.
The 2026 NTE quietly makes the description more precise. It calls NPCI a “quasi-governmental” agency, describes the 30 per cent cap as applying to TPAPs generally and acknowledges that, at the end of 2025, two U.S.-owned electronic-payment suppliers together processed more than 80 per cent of UPI transactions. At the same time, USTR continues to object that U.S. payment suppliers cannot participate in parts of the broader ecosystem, including credit transactions on UPI, on what it considers a level playing field with RuPay.
That is a much more sophisticated dispute.
The issue is not simply whether an American-owned app can succeed on UPI. Evidently it can.
The harder question is whether foreign networks obtain equivalent treatment within and alongside the underlying payments architecture.
NPCI’s Dual Character Is Where Trade Questions Become Sensitive
NPCI operates common infrastructure but also sits in an institutional ecosystem that includes indigenous products such as RuPay and NCMC.
This combination is not inherently objectionable. Countries are entitled to create national payment infrastructure.
But where an institution helps establish technical rules, controls access to infrastructure and is simultaneously associated with domestic competing schemes, foreign providers can reasonably ask how conflicts are managed.
That is why transparency matters more than labels such as “public,” “private,” “state-owned” or “quasi-governmental.”
A transparent system would allow an outside provider to understand the technical requirements, certification criteria, access conditions, fee schedules, appeal mechanisms and interoperability rules applicable to every comparable provider.
The stronger India makes that institutional architecture, the weaker the argument that domestic sovereignty necessarily translates into commercial discrimination.
Europe: Concern About Rules, Not a Finding Against UPI
The European position should not be conflated with Washington’s.
There is no comparable public European Commission document declaring UPI itself an unfair trade practice.
But the EU–India FTA negotiations concluded on January 27, 2026, and the published agreement texts include significant services, financial-services, digital-trade, transparency and good-regulatory-practice disciplines. The Commission describes the digital chapter as seeking a predictable, secure and fair environment while preserving both sides’ right to regulate for public policy, privacy and security. The texts remain subject to the required legal procedures before becoming binding.
Europe also provides an illuminating contrast on payment pricing. Regulation (EU) 2024/886 requires charges for instant euro credit transfers not to exceed those for corresponding ordinary transfers. The EU legislature expressly recognised that transaction charges influence adoption and network effects.
So regulated pricing is not uniquely Indian, and low-cost instant payments are not incompatible with an open market.
The trade-law question is less “does Government influence price?” than “are comparable providers treated comparably and are restrictions proportionate to legitimate regulatory objectives?”
UPI Free-for-All Under Threat? Bankers and Opposition Push Back on Sitharaman’s MDR Defence
China: The Cautionary Case
China demonstrates what happens when payment sovereignty and domestic preference become too closely intertwined.
In the WTO dispute China–Certain Measures Affecting Electronic Payment Services, the United States challenged restrictions benefiting China UnionPay. The panel did not uphold every American allegation; in particular, it did not simply endorse the claim of an across-the-board UnionPay monopoly over every domestic RMB transaction. But it did find violations involving specific monopoly arrangements and requirements that altered competitive conditions in UnionPay’s favour.
The market-opening process that followed was slow. The 2026 USTR report notes that American Express obtained a Chinese electronic-payment licence in 2020 and Mastercard in 2023 after lengthy delays, while USTR continued to complain about treatment of Visa. These are U.S. characterisations of China’s implementation and need to be understood as such.
China has subsequently moved to make payments easier for foreign visitors. Official Chinese guidance allows overseas users to link international cards, including Visa and Mastercard, to Alipay and WeChat Pay and has raised transaction limits.
The lesson for India is not that domestic payment infrastructure is suspect. It is that national payment policy becomes vulnerable internationally when regulatory requirements, access barriers and domestic commercial advantage cannot easily be separated.
India’s Sensitivities Are Real
India nevertheless has reasons to resist treating payment infrastructure as merely another globally tradable service.
Payments infrastructure involves financial stability, cyber resilience, fraud prevention, data access, inclusion and national continuity. The RBI’s 2018 payment-data localisation rule explicitly justified domestic storage by the need for better monitoring and “unfettered supervisory access.”
Dependence on a small number of offshore-controlled payment rails could also create concentration and strategic risks. Conversely, concentration among UPI front-end providers creates its own risks, which was the stated rationale for NPCI’s proposed 30 per cent TPAP cap.
The policy tension therefore has several dimensions simultaneously: India wants sovereign infrastructure without technological isolation, competition without systemic concentration, foreign participation without dependence, financial inclusion without permanent subsidy, and a sustainable commercial model without destroying the zero-friction character that made UPI successful.
There is no single variable that resolves all of those objectives.
UPI MDR: India’s Free Digital Payments Model Faces Its First Major Test
Lessons and the Way Forward: Publish the Ledger Before Arguing About the Fee
The most useful way forward is to frame the unresolved questions transparently rather than reduce the debate to “MDR good” versus “MDR bad.”
The first unresolved issue is UPI-specific cost accounting. NPCI’s financial statements are available, but payment-service income is aggregated across products. For public evaluation of MDR, the economically relevant disclosure would separate UPI-related switching and other revenues, attributable operating expenditure, capital expenditure, security expenditure and reserves, while making clear what costs belong elsewhere in the ecosystem.
The second is ecosystem accounting. Banks, acquiring institutions, PSPs, TPAPs and payment aggregators claim substantial unrecovered costs. Those claims can be assessed more rigorously if gross costs, existing revenues, Government incentives and identifiable banking-cost savings are presented together.
The third is MDR incidence. The formal payer is the merchant, but the ultimate economic incidence may be spread between merchant margins, customers, acquiring banks and other participants. Transaction-level data around the Rs 2,000 boundary will show whether merchants split transactions, discourage UPI or alter pricing.
The fourth is revenue allocation. Because the Government says NPCI itself does not collect the new MDR, disclosure of how the 0.4 per cent is divided among issuing banks, acquiring institutions, PSPs, applications and other participants would clarify which financing deficit the new charge is actually intended to solve.
The fifth is competitive neutrality. The cleanest international-trade principle is straightforward: comparable functions should face comparable eligibility conditions, remuneration, technical certification and access rules, irrespective of domestic or foreign ownership.
The sixth is governance separation. As UPI becomes national infrastructure, the distinction between governance of common rails and promotion of particular schemes becomes increasingly important for both domestic competition and international credibility.
The seventh is policy predictability. The India Today critique is most persuasive not as an argument about elections, but as a warning that an apparently tiny fee can become a disproportionately large trust issue if the public believes the rule can steadily expand. A published medium-term pricing framework would make future changes easier to evaluate against pre-announced principles rather than rumours.
Finally, there is an accountability issue arising directly from NPCI’s Section 8 character. Surplus is legally permissible and may be economically desirable, but because it cannot be distributed as ordinary shareholder dividend and must advance the organisation’s objects, the scale, deployment and accumulation of that surplus are relevant to the debate about how much additional economic burden needs to be placed elsewhere in the payment chain.
Conclusion: Before Asking Who Should Pay, Ask Who Already Does
The debate over UPI has become unnecessarily binary.
On one side lies the proposition that a system used by hundreds of millions of people must remain free forever because charging even a small amount would betray its original promise.
On the other lies the proposition that an enormous payments system obviously costs money and therefore MDR is self-evidently necessary.
Both propositions leave out too much.
UPI was never economically free. Banks paid fees. NPCI earned payment-service revenues and switching income. Governments provided incentives. Participants cross-subsidised operations. At the same time, UPI created scale economies and displaced part of the cost of cash, branches, ATMs and legacy payment processing.
NPCI’s own financial history makes the issue particularly interesting. A Section 8 utility that is prohibited from distributing dividends has nevertheless built substantial reserves and recurring surpluses. That is entirely lawful and may be prudent. But it means the sustainability debate cannot end with the statement that “UPI costs money.”
It must proceed to the next question:
whose costs, after which existing revenues, and after accounting for which savings?
The new MDR may turn out, after full costing, to be an efficient way of financing banks and payment providers while preserving free basic UPI. It may alternatively turn out that certain costs are overstated, particular participants are undercompensated while others are comfortably surplus-generating, or that a different division of charges would produce fewer distortions. The existing public evidence does not yet settle all of those questions.
And that is why the USTR controversy, the NPCI surplus, the India Today “peanuts” argument and the new MDR ultimately converge on one common principle:
India’s strongest defence of UPI–at home and abroad–is not merely that it is Indian or that it is cheap. It is that the rules, costs, revenues, access conditions and cross-subsidies can be shown transparently to serve a legitimate national payments objective without hidden discrimination or unexplained rent.
UPI’s first decade was about making payment effortless.
Its next decade may be about making the economics behind the payment equally transparent.
UPI Was Never Really Free: The Missing Ledger Behind India’s Digital Payments
(This is second of the 2-part series. This is an opinion piece. Views are the author’s own.)
Follow The Raisina Hills on WhatsApp, Instagram, YouTube, Facebook, and LinkedIn



About The Author