Unimech Aerospace: A ‘Buy’ Call Built on 52% Capacity Utilisation and a 17,000-Aircraft Backlog
Choice Institutional Equities just initiated Unimech Aerospace with a Buy and a ₹1,950 target — betting on a 17,000-aircraft backlog and just 52% capacity utilisation. (Image company on X)
By S. JHA
Choice Institutional Equities has initiated coverage on Bengaluru-based Unimech Aerospace and Manufacturing with a ‘Buy’ rating and a ₹1,950 target price, betting on a multi-year aero-tooling cycle. The thesis arrives despite the company’s revenue, EBITDA, and profit all declining in the very financial year the report is being published in.
Mumbai, September 29, 2026 — Unimech Aerospace and Manufacturing Ltd (UNIMECH) has been initiated with a ‘Buy’ rating and a target price of ₹1,950 by Choice Institutional Equities analysts Putta Ravi Kumar and Ashutosh Bagaria, in a September 21 report that frames the company as sitting “at the core” of a multi-decade global aerospace tooling opportunity, with precision engineering positioned as “the next growth engine.”
Against a current market price of ₹1,676, the target implies an expected share price return of 20%, with the sector view flagged as “Positive.”
The Core Business: 86% Tooling, Now Diversifying
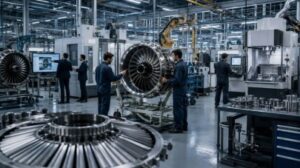
Unimech is described in the report as a Bengaluru-based, export-led precision engineering company operating on a “high-mix, low-volume, build-to-print and build-to-spec model” for global OEMs and Tier-1 suppliers, spanning aero engine and airframe tooling, MRO tools, ground support equipment, and complex precision components across aerospace, defence, nuclear, energy, and semiconductor industries.
Choice’s analysts note the company’s qualified SKU base has expanded dramatically, from 932 in FY22 to roughly 6,300 currently, with approximately 96% of revenue coming from exports across eight countries, serving customers including Boeing, Collins Aerospace, and FACC Operations GmbH of Austria.
The Investment Thesis, in Three Parts
Choice’s bullish case rests on three pillars. First, a “12+ years of aircraft backlog” argument: with roughly 17,000 aircraft on order globally and the commercial fleet projected to grow from about 30,000 planes in 2026 to 41,000 by 2036, the report argues tooling demand will compound well beyond the current aircraft upcycle, further reinforced by a global maintenance, repair and overhaul (MRO) market the analysts size at $193 billion by 2036, up from $136 billion in 2025.
Second, precision components — currently just 10% of FY26 revenue — are framed as Unimech’s “second growth engine,” backed by roughly ₹87 crore in nuclear-sector orders and a pipeline exceeding ₹400 croretied to India’s planned nuclear capacity expansion from 8.78 GW today to a targeted 100 GW by 2047.
The October 2025 acquisition of Hobel Bellows Systems, which the report says delivered approximately ₹129 crore in FY26 revenue at over 50% EBITDA margin and over 50% ROCE, is central to this shift toward higher-value assemblies, alongside a 51:49 joint venture with Saudi Arabia’s Yusuf Bin Ahmed Kanoo Group targeting the Kingdom’s industrial localisation push.
Third — and arguably the report’s most distinctive argument — Choice frames the next leg of growth as coming from utilisation rather than fresh capital spending. Installed manufacturing capacity has grown nearly sevenfold, from roughly 1 lakh machine hours in FY22 to 6.8 lakh hours in FY26, while actual utilisation sits at just ~52%, excluding a 10% allowance for first article inspection.
The analysts forecast utilisation climbing to 65% in FY27, 73% in FY28, and 78% in FY29 — meaning, in their words, “the company to grow revenue without a proportionate increase in its capacity base.”
A Bullish Report Built on a Down Year
One detail worth sitting with: Choice’s own financial tables show Unimech’s FY26 results were, in absolute terms, a decline. Revenue fell 1.0% year-on-year to ₹2,405 million, EBITDA dropped 18.4% to ₹751 million, and reported PAT fell 24.2% to ₹633 million, with EBITDA margin compressing to 31.2% from 37.9% in FY25. Choice’s own “Key Investor Questions” section addresses this directly, describing the FY26 margin compression as “largely a temporary result of the current growth and capacity expansion phase,” with recovery to 36.0% expected in FY27 and 37.0% by FY29.
The report’s SWOT analysis separately flags a concrete, quantified headwind behind part of the softness: a roughly ₹15 crore US tariff hit absorbed in Q4 FY26 specifically.
It’s also worth flagging a data inconsistency between two sections of the report itself. The cover page’s Key Financials table lists ROCE at 12.2% for FY25 and 9.7% for FY26. The SWOT/Weaknesses section, however, separately states “ROCE dilution in investment phase — 16% in FY26 vs 54% in FY25” — figures that don’t reconcile with the headline financial table elsewhere in the same document.
Readers relying on this report for precise historical return metrics should treat the Key Financials table, rather than the SWOT slide, as the more internally consistent figure, and may wish to verify against the company’s own filings.
Optionality Choice Says It Hasn’t Fully Priced In
The report lists four specific sources of potential upside not fully reflected in its base-case estimates.
Hobel is modelled to contribute roughly ₹1,960 million in FY29E revenue, with room for faster scaling.
Dheya Engineering Technologies — a 30%-owned associate developing indigenous micro gas turbine technology that Choice notes was showcased to French President Emmanuel Macron after being selected for an official Indian prime ministerial delegation to Nice — has zero profit contribution factored into estimates through FY29E, making any commercialisation pure incremental upside.
The Saudi/Kanoo joint venture is modelled conservatively at just ₹800 million of FY29E revenue against a total joint investment of $30 million. And a proposed ₹750 crore Qualified Institutional Placement, an enabling resolution the board has already approved, is earmarked for capacity expansion and “strategic acquisitions” — a phrase that leaves the door open to further M&A-driven growth beyond what’s currently modelled.
How Choice Gets to ₹1,950
The price target is derived primarily from a discounted cash flow model, using a 13.5% weighted average cost of capital and a 3.0% terminal growth rate, yielding an equity value of ₹99,125 million and a target price of ₹1,950 per share.
As a cross-check, the analysts note that applying a 50x multiple to average FY28-29E EPS of ₹39.4 implies a value of ₹1,969 — “broadly validating” the DCF output. Choice is explicit that this is a premium valuation: the stock already trades at 127.9x trailing FY26 earnings and 107.6x EV/EBITDA per the report’s own relative analysis table, multiples that compare against listed peer Azad Engineering’s 135.6x P/E and 81.2x EV/EBITDA, despite Azad posting 31.8% FY26 revenue growth against Unimech’s -1.0%.
Risks Choice Flags Directly
The report is unusually candid in listing six distinct risk categories to its own thesis: aerospace programme execution risk from slower-than-expected ramp-ups; qualification and customer-acceptance risk on new SKUs; the possibility that precision components fail to scale as a genuine second growth engine, leaving the company dependent on core tooling; margin recovery risk if subcontracting costs or weaker utilisation limit the projected operating leverage; capacity utilisation and capex risk generally; and, notably, “valuation de-rating risk” — the explicit acknowledgment that the ₹1,950 target “assumes investors continue to assign a premium multiple to Unimech’s growth profile,” and that any earnings disappointment “could result in multiple compression, even if the underlying business continues to grow.”
The Bull and Bear Scenarios
Choice’s scenario analysis frames a fairly wide outcome range around its base case.
The bull case, at ₹2,600 (63.4% upside), assumes revenue reaching ₹800-1,100 crore by FY28-29E on faster aerospace ramp-up, EBITDA margins expanding to 39-40%, and the market sustaining a roughly 55x multiple.
The bear case, at ₹1,260 (implying a 20.8% downside from the current price), assumes slower aerospace programme ramp-up, precision components remaining sub-scale for longer, and revenue reaching only ₹550-750 crore by FY28-29E — meaningfully below the base case’s ₹682-959 crore.
Ownership Structure
Shareholding data in the report shows promoter holding steady at 79.82% as of June 2026, essentially unchanged since the company’s December 2024 listing, split across six named individuals led by Chairman and Managing Director Anil Kumar P at 26.24%.
Foreign institutional ownership remains minimal at just 0.43%, while domestic institutions — including Valuequest S C A L E Fund and Vq Fastercap Fund — hold a combined 5.60%. Public shareholding has crept up gradually from 11.98% at listing to 14.16% by June 2026.
(This news analysis is intended for informational purposes only and is not investment advice. Readers should conduct their own due diligence or consult a SEBI-registered financial advisor before making investment decisions.)
Follow The Raisina Hills on WhatsApp, Instagram, YouTube, Facebook, and LinkedIn



About The Author