Sigma Advanced Systems: Inside the Company Trying to Build a Global Aerospace Platform From a Defunct Telecom Shell
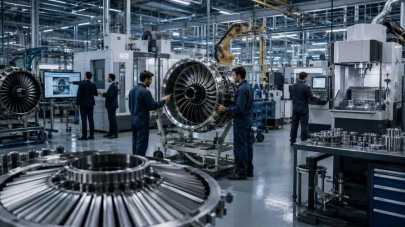
Sigma Advanced Systems went from a defence electronics business to a Rolls-Royce supply chain player in under a year (Image company on X)
By S. JHA
A Hyderabad defence electronics maker has spent the past year acquiring its way into the Rolls-Royce supply chain, reverse-merging into a dormant listed telecom company, and raising ₹4.6 billion to shift UK manufacturing to a Special Economic Zone outside Chennai. A new Nuvama visit note lays out the strategy — and the financial history behind it is anything but conventional.
Mumbai, September 27, 2026 — Sigma Advanced Systems Ltd (SASL) is positioning itself as a global aerospace and defence supplier built around relationships with major original equipment manufacturers, chiefly Rolls-Royce, according to a September 21 visit note from Nuvama Institutional Equities analysts Subhadip Mitra, Srishti Gandhi, Divyam Sureka, and Vikram Datwani.
The note carries no formal rating or 12-month price target — Nuvama’s key data table lists both as “Not-Rated” and “NA” respectively — meaning this is a company-overview publication rather than a buy or sell call, even as it lays out a detailed and fast-moving corporate transformation story.
From Defence Electronics Shell to Rolls-Royce Supplier
The company’s origins trace back to 1994, when Cheemarla Damodar Reddy and Sanjay Pukalay established a Hyderabad-based defence electronics manufacturer serving India’s Defence Research and Development Organisation (DRDO), defence public sector undertakings, and the armed forces, according to Nuvama.
The listed entity carrying that business today, however, began life as something entirely different: Megasoft Limited, a telecom software company. The two were combined through an NCLT-sanctioned Scheme of Amalgamation — with the order dated December 16, 2025, made effective December 31, 2025, and an appointed date retroactively set to April 1, 2024 — before the listed entity was renamed Sigma Advanced Systems on January 12, 2026.
Nuvama’s note flags an important consequence of that structure directly: “FY26 consolidated financials are not comparable with FY25 as the reported FY25 base represents a materially different enterprise.”
Three Acquisitions in Under a Year
Since October 2025, Sigma has assembled its aerospace platform through a rapid sequence of overseas acquisitions. Nuvama’s timeline shows the company acquired 100% of UK-based Nasmyth Group in October 2025 for ₹2.1 billion — a transaction funded almost entirely through the assumption of roughly ₹2 billion in existing debt rather than cash — bringing precision engineering capabilities in aero-engine components.
That was followed by a 51% stake in Delhi-based AS Strategic in April 2026, later increased to 76% in August 2026 via a share swap, providing access to European defence joint ventures including EM&E and Arquimea.
In July 2026, Sigma acquired 100% of Leicester-based Bromford Precision Solutions for £11.9 million (₹1.5 billion), adding Rolls-Royce-approved manufacturing capabilities in aero-engine rings, compressor casings, and lock plates.
The company simultaneously exited a non-core holding: in March 2026, Sigma sold its 36.5% stake in Swiss pharmaceutical company Extrovis AG for ₹1.4 billion, which Nuvama’s note describes as “effectively removing the group’s non-A&D exposure.”
A ₹4.6 billion preferential allotment completed in July 2026 is funding facility modernization, expanded Indian manufacturing, and further acquisitions, backed by promoter group iLabs, led by Srini Raju, which Nuvama notes has managed over $1 billion across investment funds and co-founded Sri City, a 7,000-acre industrial hub housing more than 240 companies from 31 countries.
The Business Today: Three Verticals, Three Very Different Margin Profiles
Nuvama’s note breaks Sigma’s single reported accounting segment into three commercially distinct verticals as of Q1 FY27. Aerospace, predominantly the acquired UK platform, contributed ₹2.29 billion, or 61% of quarterly revenue, but carries the thinnest margins at 10-14% EBITDA, with contract tenors of 5-7 years; the note specifies that 75-80% of aerospace revenue comes from commercial aerospace programmes — spanning Rolls-Royce’s Trent engine family, the UltraFan, and airframe programmes including the B787, A320, A350, Eurofighter, F-35 and Gripen — rather than defence, making commercial aircraft production rates a key demand driver.
Defence exports, focused on 155mm base-bleed shell bodies, filled fuzes, and allied assemblies for North American and European customers, generated ₹1.04 billion at considerably richer 22-28% margins, with faster 1.5-2 year contract cycles that Nuvama links directly to “the ongoing NATO ammunition replenishment cycle.”
The smallest vertical, legacy domestic defence, generated just ₹410 million but carries the highest margins of the three, at 25-30%, spanning missile subsystems for India’s LRSAM/MRSAM and VSHORADS programmes, avionics for the Su-30 and Hawk 132, and counter-drone technology through Sigma’s 37.8% associate stake in Indrajaal Drone Defence India — a segment Nuvama describes as “the most IP-intensive part of the portfolio, although its contribution to consolidated earnings is currently constrained by its small revenue base.”
An ₹97 Billion Order Book, and a Bet on Sri City
Sigma’s consolidated order book stood at approximately ₹97 billion as of Q1 FY27, per the note, split roughly 80% aerospace (executable over five to seven years) and 20% defence domestic and exports (executable over one to two years) — a mix management is using as the foundation for what Nuvama describes as the company’s “first ₹50 billion annual revenue milestone” target.
The centerpiece of the company’s medium-term margin story is a 23-acre SEZ facility at Sri City, intended to absorb manufacturing work transferred from the UK.
Nuvama’s note lays out management’s stated timeline: operations commencing in Q3 FY27, fabrication, surface treatment and non-destructive testing capabilities coming online in Q4 FY27, a 200-400 basis point EBITDA margin benefit through FY27, and a further 400-600 basis points through FY28.
In just eight months, the company had already operationalized 75,000 of a planned 500,000 square feet at the campus, with 100,000 annual machining hours of capacity targeted to rise to roughly 300,000 hours at the first facility.
Nuvama frames the stakes plainly: “Conversely, any delay in localisation would leave Sigma predominantly exposed to the acquired low-teens-margin aerospace business while the group continues to carry acquisition-related goodwill and the associated balance-sheet burden.”
A Financial History That Reflects the Restructuring, Not Steady-State Operations
Investors examining Sigma’s historical financials in Nuvama’s tables should read them with the reverse-merger context firmly in mind.
Reported revenue swings from ₹20 million in FY23 to effectively zero in FY24, then to ₹1.07 billion in FY25 and ₹4.92 billion in FY26 — a trajectory reflecting corporate restructuring and acquisition accounting rather than organic like-for-like growth.
Valuation multiples in the same tables are similarly volatile: Nuvama’s data shows a diluted P/E ratio of 548 times in FY23, 831 times in FY24, a negative 452 times in FY25 (reflecting that year’s net loss), and 56 times in FY26.
Adjusted profit of ₹2.68 billion in FY26 sits well above the year’s EBITDA of just ₹480 million, a gap Nuvama’s income statement attributes substantially to other income of ₹2.96 billion and a tax provision of only ₹334 million — underscoring that a meaningful share of FY26’s reported profitability came from non-operating items (including gains associated with the Extrovis AG stake sale) rather than from the core aerospace and defence operating business alone.
Shareholding data in the note also shows promoter holding falling from 71.22% in both December 2025 and June 2026 to 66.24% by July 2026 — a roughly five-percentage-point reduction in a single month, consistent with the dilutive effect of the ₹4.6 billion preferential allotment completed that same month, though promoter ownership remains the clear majority.
Return on average equity, per Nuvama’s data, swung from 5% in FY23 and 4% in FY24 to negative 7% in FY25 before jumping to 83% in FY26 — another figure that reflects the one-off, restructuring-driven nature of the past year’s reported results rather than a stable, repeatable operating return.
(This news analysis is intended for informational purposes only and is not investment advice. Readers should conduct their own due diligence or consult a SEBI-registered financial advisor before making investment decisions.)
Whirlpool India Shares Surge 5% as Promoter Stake Sale Plans Stay in Focus
Follow The Raisina Hills on WhatsApp, Instagram, YouTube, Facebook, and LinkedIn



About The Author