ESDS Software Turned a Multibagger in Days — Now the Exchange Wants Answers, and So Should Investors
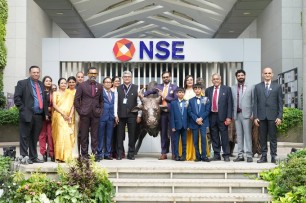
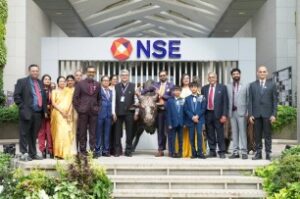
ESDS IPO listing: Shares make their stock market debut as investors watch the company’s performance. (Image BSE on X)
By S. JHA
A 300%-plus gain from IPO price within a week of listing is the kind of story that makes headlines. It’s also exactly the kind of move that puts a stock under formal exchange scrutiny — which is precisely what’s happened here.
Mumbai, September 13, 2026 — ESDS Software Solution Ltd has delivered one of the most explosive post-listing runs seen on Indian exchanges this year, turning a ₹429 IPO share into a stock trading above ₹1,700 within a week — a gain of roughly 300%.
But the rally has been accompanied by something less celebratory: an exchange-sought clarification over the stock’s price movement, and its placement under the Additional Surveillance Measure (ASM) framework.
For investors sitting on paper profits, understanding what’s actually driving this move — and what isn’t — matters more now than the headline percentage gain.
How the Rally Unfolded
ESDS Software, a Nashik-based AI-enabled cloud, managed services and data-centre infrastructure provider, priced its ₹720 crore IPO in a band of ₹408-429 per share, with the issue subscribed 135.88 times overall — including 261.51 times in the qualified institutional portion — on bids worth roughly ₹72,000 crore.
The stock’s actual trading history since its September 4 listing has been extraordinary even by hot-IPO standards. It listed at ₹757 on the NSE, a 76.46% premium over its issue price, and closed its first session up 111.75% at ₹908.40.
It then hit consecutive upper circuits — 20% on its second and third sessions, then 10% circuits for a fifth straight session by September 11 — before touching a fresh high of ₹1,740.40 that same day, according to INDmoney, a level representing gains of roughly 306% over the IPO price and 130% over its own listing-day low.
The Exchange Steps In
That pace of gains didn’t go unnoticed by regulators. Data from Screener.in shows the exchange sought formal clarification from ESDS Software on September 9 specifically “with reference to significant movement in price.”
The company’s response, as reported by Business Today, was direct: “the Company is not aware of any specific reason for the significant movement in the price of its security… Such movement is purely market driven and may be attributable to a combination of factors, including prevailing market conditions.”
Some post-listing profit-taking has already begun: Groww notes the stock fell 8% at one point after its initial 235% surge, characterizing the pullback as “a pause after an exceptional debut-driven rally” rather than a reversal.
Manika Plastech IPO: Should You Apply? Financials Look Strong, But Where Is the Order Book?
The Story Behind the Story: A $1.25 Billion AI Bet
The rally isn’t happening in a vacuum — it’s tied to a specific, large commercial narrative. Business Today reported that ESDS’s $1.25 billion AI infrastructure contract, reportedly with a company called Sharon AI, has been cited repeatedly by brokerages as a central driver of the stock’s re-rating, alongside broader enthusiasm for India’s cloud and AI infrastructure buildout.
Choice Institutional Equities, which initiated coverage with a ‘Buy’ rating and a 12-month target price of ₹1,550, projected the company’s revenue could grow from ₹470 crore in FY26 to ₹2,260 crore in FY27E and ₹4,580 crore in FY28E, alongside deployment of roughly 8,208 NVIDIA B300 GPUs and ₹570 crore in capital expenditure.
Dharmesh Kant, Head of Equity Research at Chola Securities, offered a similarly constructive but more measured take, telling Business Today that ESDS is well-positioned within India’s data-centre ecosystem and flagging the company’s Australian joint venture as a further potential catalyst — while explicitly advising investors considering the stock to “keep a two-to-three-year horizon in mind,” with potential for the stock to double from then-current levels over that period rather than in days or weeks.
Why the Valuation Math Is Worth a Hard Look
Here’s the detail that deserves the most attention from anyone currently sitting on profits: Choice’s own 12-month target price of ₹1,550 was set when the stock traded well below that level — and the market has already blown past that target within days of the brokerage issuing it, with the stock touching ₹1,740 by September 11.
When a stock’s market price overtakes even its most bullish covering analyst’s 12-month target within a single week of that target being issued, it’s a signal that price action has decoupled from the fundamental thesis originally used to justify it.
The valuation metrics reinforce that disconnect. India Infoline’s data from September 8 — when the stock traded around ₹1,272, well below its subsequent peak — already showed a trailing P/E ratio of 207.46 and a price-to-book ratio of 10.83.
Screener’s data shows the company’s actual FY26 total income was ₹480.65 crore, against a market capitalization that has ranged between roughly ₹18,500 crore and ₹20,400 crore in the days since listing — a price-to-sales ratio north of 40 times for a company whose five-year profit CAGR, while a genuinely strong 84.3%, was built on a far smaller revenue base than the market is now pricing in.
Coforge Board Crisis: How a Hidden Chairman Rating Triggered a Boardroom Shake-Up
The Risks Even the Bulls Are Flagging
Even Choice’s bullish note came with explicit caveats. It flagged “AI deal execution, customer concentration, high capex intensity and competition as key risks,” specifically warning these factors “could delay the earnings ramp-up and put pressure on utilisation, margins and returns.”
In other words, the same $1.25 billion contract driving the bull case is also the company’s single largest concentration risk — its scale is exactly what makes both the upside and the downside so significant if execution falters.
What This Means for Investors Sitting on Gains
For anyone who caught this IPO and is now sitting on tripled or quadrupled money, a few structural factors are worth weighing rather than any single piece of advice:
The stock’s current price already exceeds the target price set by its most prominent bullish coverage — meaning further gains from here require either upward target revisions from brokerages or continued momentum-driven buying disconnected from published valuation models.
The company itself has stated it sees no specific fundamental reason for its price movement, and regulators have flagged the stock for closer surveillance. Ownership data from India Infoline shows public shareholders already hold nearly 50% of the company just days after listing, meaning a large float is available to trade freely — a dynamic that can support liquidity but also means less structural scarcity than stocks with heavier promoter or institutional lock-ins in their early days.
And the central growth driver — the Sharon AI contract — remains, by the covering brokerage’s own admission, unexecuted and concentrated, not yet proven.
None of this means the stock’s fundamental story is false — India’s cloud and AI infrastructure buildout is real, and ESDS’s positioning within it may well justify significant growth over a multi-year horizon, as Chola Securities’ Kant argued.
But the gap between a multi-year growth thesis and a multi-day, ASM-flagged trading rally is exactly the gap investors holding paper profits should be thinking about now, rather than assuming the two are the same thing.
(This article is intended for informational purposes only and is not investment advice, and does not constitute a recommendation to buy, hold, or sell any security. Readers should conduct their own due diligence or consult a SEBI-registered financial advisor before making investment decisions.)
Tata Sons Listing: Why Afcons Infrastructure Could Be the SP Group Stock to Watch
Follow The Raisina Hills on WhatsApp, Instagram, YouTube, Facebook, and LinkedIn



About The Author