Coforge Board Crisis: How a Hidden Chairman Rating Triggered a Boardroom Shake-Up
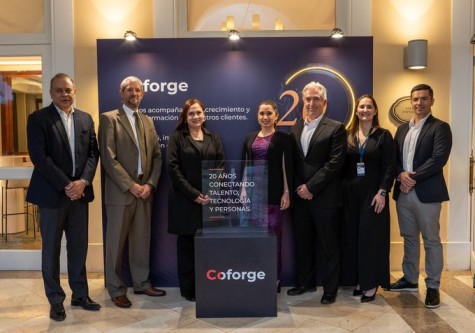
Coforge’s boardroom crisis has raised questions over corporate governance and the handling of board evaluations.
By P. SESH KUMAR
A board evaluation that was not fully shared with directors has triggered a rare corporate-governance crisis at Coforge, bringing its chairman and nomination and remuneration committee chair under scrutiny.
New Delhi, September 12, 2026 — In the second week of September 2026, Coforge Limited, the Noida-headquartered IT services company that had just absorbed the engineering firm Encora in a USD 2.35-billion all-stock deal, lost its chairman and the chair of its nomination and remuneration committee inside seventy-two hours. The trigger was no fraud, restatement or whistle-blower but a board evaluation report. The company says its internal auditor found that the reports were seen only by the chairman, O. P. Bhatt, and the committee chair, D. K. Singh, and that the chairman’s lowest rating was never placed before the committee or the board, even as that committee recommended him for five more years.
Prologue: A Rating Nobody Was Allowed to Read
Every schoolchild knows the oldest trick in the satchel. The report card with the red mark in mathematics comes home late, creased, or not at all. What no schoolchild is ever allowed to do is sit on the committee that decides whether he goes up to the next class while holding the only copy of his own report.
At Coforge Limited, on the company’s own account to the stock exchanges, something uncomfortably close to that arrangement operated at the very summit of the board.
In a filing made late on the night of 10 September 2026, Coforge said its internal auditor had found that the reports arising from the board’s annual evaluation for 2025-26 were available only to the chairman, O. P. Bhatt, and to the chair of the nomination and remuneration committee, D. K. Singh, and were withheld from the rest of the board, independent directors included, on the chairman’s instructions.
The findings were presented orally, without copies, and the presentation did not cover everything that mattered. Most tellingly, the filing said, “the Chairman’s category received the lowest rating,” and that finding was neither disclosed nor discussed before the committee or the board.
What followed had the tempo of a thriller rather than a compliance file. Bhatt, a former chairman of the State Bank of India, resigned on 8 September while the board was still weighing his explanation.
On 10 September Singh sent in his own resignation, pointing to tension between the independent and the executive directors; the company answered, in the very filing that disclosed his exit, that the allegation was “unfounded and more pertinently appears as an afterthought.”
Hovering over it all was Advent International, the private-equity house that had become Coforge’s largest shareholder through the Encora transaction and that had voted, a fortnight earlier, against Bhatt’s reappointment.
What Coforge Is, and Why Its Boardroom Matters
If we strip away the jargon, Coforge is the contractor that rewires the house while the family is still living in it. Banks, insurers, airlines, healthcare companies and public bodies, mostly in the United States, Britain and Europe, hire it to build, run and modernise the software on which their businesses depend: moving systems to the cloud, engineering data platforms, testing applications, running back-office processes and, increasingly, stitching artificial intelligence into all of it.
It presents itself as a firm of more than 45,000 professionals organised around industries such as banking and financial services, insurance, travel and healthcare. Its chief executive, Sudhir Singh, also chairs the listed testing specialist Cigniti Technologies, in which Coforge acquired control in 2024.
The pedigree is older than the name. The company was born in 1992 as the software-services arm of the NIIT group and traded for years as NIIT Technologies. In 2019 Baring Private Equity Asia bought the founders’ 30.6 per cent stake and enlarged its holding through an open offer; the rebranding to Coforge followed in 2020.
By August 2023 Baring had sold out altogether, leaving behind a rare creature on Dalal Street: a large, professionally managed, promoter-less company owned almost entirely by institutions and the public.
Then came the deal that changed the arithmetic of the boardroom. In December 2025 Coforge agreed to buy Encora for about USD 2.35 billion, paying in shares; Encora’s sellers, among them Advent and Warburg Pincus, received roughly a fifth of the enlarged equity.
On completion on 23 April 2026, Coforge allotted about 9.38 crore shares at Rs 1,815.91 apiece, some Rs 17,033 crore in all, and two Advent executives, Shweta Jalan and Atin Jain, joined the board as non-executive, non-independent directors nominated by the Advent-linked sellers.
The first quarter with Encora on the books showed why investors cared: revenue of USD 592.2 million, up a third in dollar terms, an EBIT margin of 16 per cent and a record twelve-month executable order book of USD 2.23 billion.
The storm, in other words, broke over a ship that was sailing well. That is exactly why it deserves attention. Boards seldom come apart over a bad quarter; they come apart over who holds the chair and who holds the pen.
A Quiet Court Order Just Shook India’s Audit and NFRA Regime
The Chronology: Eight Weeks from Reappointment to Resignation
Bhatt joined the board as an independent director for three years from 1 May 2024 and became chairman on 29 June that year; his term was due to lapse in April 2027. The board evaluation for 2025-26, the annual self-assessment every listed company must perform, was conducted in March and April 2026.
In April the company also finalised its internal audit plan for 2026-27, and its scope, unusually, reached into processes labelled “Hire-to-Retire” and the accuracy and completeness of board reporting. The Advent nominees took their seats in the same month.
By July the board, acting on the recommendation of the nomination and remuneration committee, had put Bhatt forward for a second term of five years, running to 2032. Because he had turned 75, and because the reappointment of an independent director needs it in any event, the resolution had to clear the 75 per cent bar of a special resolution.
The Press Trust of India reports that Bhatt had agreed with the board in July to accept that second term. An automated market summary of the 27 July results meeting goes further and records the board re-appointing him as chairperson; that detail is single-source and should be read with caution.
Then the ground moved. According to The Economic Times, KPMG, the internal auditor, red-flagged the handling of the evaluation in early August and key investors confronted Bhatt with its findings; this timing rests on a single line of reporting and does not appear in the company’s filings.
At the thirty-fourth annual general meeting on 24 August, the special resolution drew 65.4 per cent in favour and 34.5 per cent against, short of the threshold, with Advent among those voting no.
The board then set out its concerns and asked the chairman for an explanation. He gave one, and before the board had finished considering it he resigned on 8 September, describing his conduct as “good faith actions” in the evaluation process.
Staying on while the disagreement persisted, his letter said, would not be conducive to the effective functioning of the board. The shares fell as much as 9 per cent in trade on 9 September and closed about 5 per cent lower, and the company hurried out a clarification that the matter touched neither its financial statements nor its reporting nor its guidance.
On the night of 10 September, it published the auditor’s detailed observations. Reports relaying Moneycontrol add that the auditor examined the original evaluation report, board records and recordings of the meetings at which the findings were presented, and found the version shown to directors did not match the original; that account is single-origin and goes beyond the filings.
On 11 September the company disclosed Singh’s resignation, rebutted it, reconstituted the committee under Beth Boucher and confirmed Vivek Sharma as interim chair until 31 January 2027, charged with a search for new independent directors.
The Plumbing, Explained Simply: Who Is Supposed to Do What
The episode makes sense only once four pieces of corporate plumbing are understood, together with the two big words that sit above them. Here they are, one pipe at a time.
The report card: board evaluation. Since the Companies Act, 2013 and SEBI’s Listing Regulations of 2015, every listed board must grade itself each year: the board as a whole, each committee, each director and the chairperson.
The nomination and remuneration committee specifies how the evaluation is to be done, whether by the board, by the committee or by an external agency, and reviews its implementation under section 178(2); the board’s report must tell shareholders how it was done under section 134(3)(p). Independent directors are evaluated by the entire board, and the director being evaluated does not take part, which is the proviso to Regulation 17(10) and the burden of paragraph VIII of Schedule IV.
The independent directors must also meet at least once a year without management to review the performance of the non-independent directors, the board and, pointedly, the chairperson, taking in the views of executive and non-executive directors, and to judge whether information reaches the board in adequate quantity, quality and time. SEBI’s 2017 guidance note fills in the method, down to feedback for those evaluated and an action plan. Put simply, the report card exists so that the people who decide whether a director stays have evidence rather than impressions. It is not a private diary. It is the board’s own file.
The selection-and-pay committee: the NRC. The nomination and remuneration committee is the board’s search committee and pay committee rolled into one. It consists wholly of non-executive directors, is dominated and chaired by independents, and while the company’s chairperson may sit on it, he may not chair it. Its charter in Part D of Schedule II to the Listing Regulations is to set the criteria for qualifications, independence and performance evaluation, to identify and recommend directors, to recommend the pay of senior management and, in the clause that matters most here, to decide whether to extend or continue the term of an independent director on the basis of the report of performance evaluation. Paragraph VIII of Schedule IV says the same thing from the other side.
In plain English, the committee’s recommendation on a reappointment is meant to be the conclusion of a syllogism whose major premise is the evaluation. If we remove the premise, the conclusion floats in the air.
The watchdog: the audit committee and the internal auditor. A common confusion needs clearing first: the audit committee does not grade directors. Its business is the integrity of numbers and the soundness of controls. Under section 177(4) of the Act it oversees financial reporting, recommends and supervises the statutory auditor, and evaluates internal financial controls and risk management; under Part C of Schedule II to the Listing Regulations it reviews the adequacy of the internal audit function, discusses significant findings with the internal auditors, and reviews internal investigations into suspected fraud, irregularity or material failures of internal control before reporting them to the board.
The internal auditor is appointed under section 138, and its scope and methodology are to be settled by the audit committee or board in consultation with it under rule 13 of the Companies (Accounts) Rules, 2014.
At Coforge the internal auditor, KPMG, was working to a plan that included the accuracy and completeness of board reporting, and that is how a boardroom ritual normally inspected by nobody came to be inspected by an auditor. It is also why the proxy adviser IiAS called an internal audit of a board evaluation “an unheard event in a normal course.” The audit committee, then, did not evaluate the directors; it owned the audit that evaluated the evaluation. The distinction will matter when the defence takes the stand.
(This is first of the two-part series. This is an opinion piece. Views are the author’s own.)
Follow The Raisina Hills on WhatsApp, Instagram, YouTube, Facebook, and LinkedIn



About The Author