MMDR Amendment Act 2026: Why Odisha Fears Loss of Mining Revenue and Fiscal Autonomy
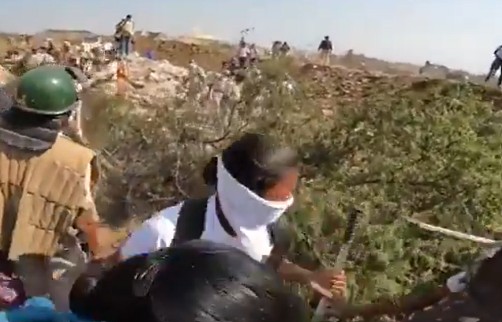
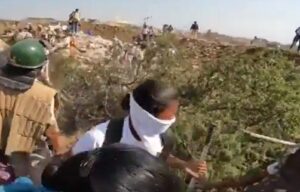
Odisha Bauxite mining protest (Image video grab)
By PRADEEP KUMAR PANDA
The amended mining law has triggered economic, political and constitutional concerns in Odisha over State levies, past dues and Centre–State fiscal powers.
Bhubaneswar, September 27, 2026 — The Mines and Minerals (Development and Regulation) Amendment Act, 2026 (MMDR Amendment Act, 2026) amends the parent 1957 Act. It was passed by Parliament in mid-August 2026 (Lok Sabha on 12 August with minimal discussion, Rajya Sabha on 13 August) and notified shortly thereafter.
Key changes include:
- Expansion of Section 2 so that “regulation of mines” is followed by “and mineral-bearing land,” bringing mineral-bearing lands more firmly under central regulatory control.
- Insertion of new Section 9D, which states that no tax, cess or other levy (by whatever name) shall be imposed by a State Government on mineral rights or mineral-bearing lands (whether based on quantity, value, royalty or otherwise), except in accordance with conditions or restrictions prescribed by the Central Government.
- Treatment of past unpaid/unrecovered levies as invalid (amounts already collected need not be refunded).
- Amendment to Section 13 empowering the Centre to frame rules prescribing the conditions under which States may impose such levies.
Odisha, which accounts for a very large share of India’s mineral wealth (estimates often cited around 44% in political discourse) and generates substantial mining-related revenues (royalties, auction premiums, DMF contributions, etc.), has been at the centre of opposition to the Act. Critics (primarily the Biju Janata Dal/BJD, other opposition parties, and some analysts) highlight significant concerns under economic, political and constitutional heads. The Central Government and the ruling BJP in Odisha counter that core existing revenues (royalties, auction premiums, DMF) remain with the States, that the Act creates uniformity and predictability to attract investment, and that it does not take away States’ rights over land or minerals in the manner claimed.
Economic Loss: Odisha’s mining sector is a major contributor to State revenues (historically a large share of non-tax revenue; mining has been projected in the range of 30–40% of certain revenue categories in recent budgets). The main claimed economic impacts are:
Loss of arrears/outstanding dues (one-time hit of ₹1 lakh crore+): Following the Supreme Court’s 2024 nine-judge Constitution Bench ruling in Mineral Area Development Authority v. Steel Authority of India (and related orders), States were held to have power to tax mineral rights and mineral-bearing lands. The Court allowed recovery of arrears from 1 April 2005 onwards (without interest/penalty, payable in staggered instalments over years). Odisha’s potential claim has been estimated at over ₹1 lakh crore (some political statements put it higher, e.g., ₹1.2 lakh crore for 2005–2026).
A large portion is linked to the Odisha Rural Infrastructure and Socio-Economic Development (ORISED) Act, 2004 (which had provided for a tax of up to 20% of the annual value of mineral-bearing land; earlier struck down but revived in principle by the 2024 ruling). Section 9D of the 2026 Amendment deems unpaid/unrecovered levies invalid. This extinguishes the bulk of the potential windfall. Already-collected amounts need not be refunded, creating an asymmetric outcome.
Annual recurring revenue loss (estimated ₹12,000 crore+): Opposition estimates that restrictions on new/additional State levies on mineral rights or mineral-bearing lands will cost Odisha around ₹12,000 crore per year going forward. This is framed as the inability to impose or collect taxes/cesses beyond the Centre-prescribed framework.
Mining in Odisha involves multiple charges (royalty, auction premium, dead rent, DMF, GST, transit fees, etc.—around 14 types often cited). While the Centre maintains that royalty, auction premiums (Odisha earned ~₹87,000 crore from premiums between 2020–21 and 2023–24 from operationalised blocks) and DMF continue to flow primarily to the State (claims of ~90% or more of relevant mining revenues remaining with States), critics argue the Act curtails the State’s future ability to design additional resource-based levies for development needs.
Broader fiscal and developmental impact: Mining districts often bear environmental, social and infrastructure costs. Reduced fiscal autonomy could constrain spending on education, health, irrigation, rural development and mitigation in affected areas. Odisha’s heavy reliance on mineral revenues makes any restriction particularly painful for a State that has used these resources to fund development. Critics also argue that waiving arrears primarily benefits lease-holders/miners (described by some as “crony capitalists”) at the expense of State finances.
The Centre’s counter is that multiplicity and unpredictability of State levies deter investment in capital-intensive mining; uniformity will expand overall activity, auctions and long-term revenues for States, and existing core streams are protected.
The economic critique is that Odisha faces a large immediate loss of recoverable arrears plus constrained future revenue-raising capacity from its most valuable natural resource base, with knock-on effects on the State budget and development programmes.
Political Issues: The Act has become a major political flashpoint in Odisha:
Opposition mobilisation: The BJD (main opposition, previously in power for 24 years under Shri Naveen Patnaik) has described the passage as a “black day for Odisha,” written to the Chief Minister and BJP MPs demanding rollback, sought the President’s intervention via the Governor, staged protests, and threatened an economic/commercial blockade. It frames the law as anti-Odisha, an attack on federalism, and a transfer of control over the State’s mineral wealth to the Centre/corporates. The broader INDIA bloc has announced agitations, including a planned gherao of the Odisha Assembly.
Ruling side’s defence and intra-State dynamics: The BJP-led State government and central leaders (e.g., responses from figures like Dharmendra Pradhan) argue the criticism is a “false narrative,” that 90%+ of mining revenues stay with the State, that 2015 reforms already dramatically increased Odisha’s mining revenues (from ~₹5,000 crore annually pre-2014 levels to much higher figures via auctions and higher royalty), and that the Act protects local industry, employment and investment while preventing predatory multi-level taxation. The State government has been accused by the opposition of remaining silent or supporting the Centre despite the claimed losses.
Federal and national political dimensions: The issue is portrayed by critics as part of a broader centralisation trend that weakens resource-rich (often opposition-ruled or previously opposition-ruled) States.
Similar concerns have been raised by other mineral States (Jharkhand, Karnataka, Kerala, Telangana, etc.), some of which have moved or plan to move the Supreme Court. Passage with very limited debate in the Lok Sabha is cited as evidence of insufficient parliamentary scrutiny of a law with far-reaching State-level consequences. Politically, it sharpens Centre–State tensions and provides opposition parties a platform to mobilise around regional identity, resource rights and federalism.
The political contest is thus over narrative control (fiscal autonomy and “Odisha’s rights” vs. national uniformity, investment and protected core revenues) and over who is seen as defending or undermining the State’s interests.
Odisha’s ₹42 Lakh Crore Investment Story: Where Is the Ground Reality?
Constitutional Point of View: Constitutional objections form the deepest layer of criticism: Federal structure and distribution of legislative powers: The Constitution assigns to States power over land and buildings (Entry 49, State List) and taxes on mineral rights (Entry 50, State List), subject to any limitations Parliament may impose by law relating to mineral development (linked to Entry 54, Union List).
The 2024 Supreme Court nine-judge Bench majority recognised States’ power to tax mineral rights and that mineral-bearing land can fall within States’ taxation power over land; it also clarified that royalty is not a tax. Critics argue Section 9D (and the expansion of Section 2 to “mineral-bearing land”) goes beyond permissible “limitations” and effectively operates as a near-blanket prohibition on State taxation in this field, reducing States to “supplicants” dependent on Central rules. This is said to disturb the federal balance and cooperative federalism.
Override of Supreme Court judgment: The 2026 Amendment is widely characterised by critics as an attempt to legislatively nullify or substantially undo the financial consequences of the 2024 SC ruling (especially the arrears recovery direction).
While Parliament can amend the law within its competence, a retrospective invalidation of dues that a Constitution Bench had enabled raises questions about whether an ordinary statute can render a judicial determination of rights ineffective in this manner. Some analyses suggest the retrospective extinguishment of unpaid levies is a particularly vulnerable aspect. Challenges under Article 131 (State vs. Union) or writ jurisdiction are already underway or announced from multiple States.
Legislative competence and equality concerns: Extending the bar to taxes on mineral-bearing lands (potentially under Entry 49) is argued by some to exceed what Entry 50 limitations allow and may require a constitutional amendment rather than ordinary legislation. The differential treatment (already-collected amounts protected; unpaid ones invalidated) has been criticised as arbitrary and contrary to equality principles.
The Centre’s position is that the amendments are a valid exercise of its powers over mineral development in the public interest, aimed at creating a uniform national fiscal framework, and that States retain core revenues and control over minor minerals.
In essence, the constitutional critique is that the Act centralises control over a key State List subject in a manner inconsistent with the 2024 SC interpretation of federal taxing powers, undermines fiscal federalism, and attempts to override judicially recognised State entitlements through ordinary legislation.
Odisha is the sharpest site of contestation because of the scale of its mineral endowment and the size of the claimed arrears. Legal challenges by other States are progressing; political agitation continues in Odisha.
The Centre maintains the Act protects State interests while promoting orderly national development of minerals. Independent assessments note that while existing royalty/premium/DMF streams are largely preserved, the restriction on additional State levies and the treatment of past dues represent a real shift in fiscal space and control. The ultimate resolution is likely to rest with the Supreme Court on the constitutional questions.
(This is an opinion piece. Views expressed are the author’s own.)
₹12,000 Crore Question: Why Odisha Is at the Centre of India’s Mining Revenue Battle
Follow The Raisina Hills on WhatsApp, Instagram, YouTube, Facebook, and LinkedIn



About The Author